What are Accruals?
Accruals describe revenues earned and expenses incurred on the income statement, irrespective of whether cash was actually received or paid by the company.

Accruals describe revenues earned and expenses incurred on the income statement, irrespective of whether cash was actually received or paid by the company.
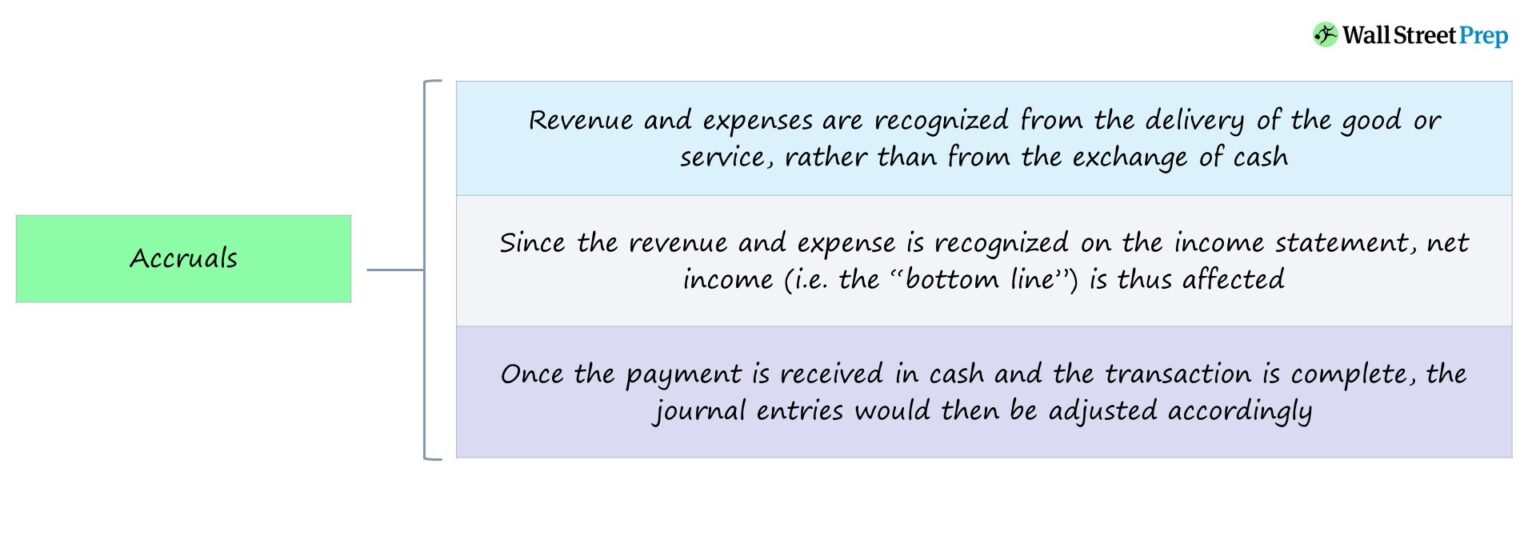
The concept of accruals is the basis of accrual accounting, in which a company’s revenue and expenses are recognized at the delivery of the good or service, rather than from the exchange of cash.
By definition, any revenue or expense recognized on a company’s income statement but not yet recorded in their corresponding accounts because of the unresolved nature of the transaction is known as an “accrual”.
However, since the revenue or expense is recognized on the income statement, net income — i.e. the “bottom line” — is affected.
Per GAAP accounting standards, revenue is recognized once the good or service is delivered to the customer (and thus “earned”), even if the customer has not yet fulfilled their obligation to pay the company in cash.
In contrast, cash-basis accounting only records revenue or expenses after the customer has issued a payment in the form of cash.
Given how transactions are typically completed today — e.g. purchases where customers pay using credit — the use of accruals is perceived as a more accurate measure for estimating a company’s near-term revenue and expenses.
Hence, accrual accounting has become the standardized approach for bookkeeping under GAAP.
Accrued revenue is defined as goods or services provided to a customer, however, the company has not yet received payment in cash.
Suppose a SaaS company has delivered its services to a company and has sent an invoice to the customer stating the amount due.
Upon delivery of the service, the journal entries are a debit to the accounts receivable account and a credit to the revenue account.
Once the payment is received in cash (to satisfy payment of the outstanding invoice), the company would record a credit to the accounts receivable account and a debit to cash, as that signifies that the payment was collected by the company.
As an example, a company could hire a consultant and receive their services before an actual cash payment is processed.
Like accrued revenue, the consultation fees are recognized on the income statement in the current period despite the company still being in possession of the cash.
The expense would be recorded regardless of whether the consultant had received their expected cash payment for their delivered services.
Once the payment is received in cash and the transaction is complete, the journal entries would be adjusted accordingly.

Enroll in The Premium Package: Learn Financial Statement Modeling, DCF, M&A, LBO and Comps. The same training program used at top investment banks.


No comments yet.