What are Net Identifiable Assets?
Net Identifiable Assets, in the context of M&A, refer to the fair value of an acquisition target’s assets once the corresponding liabilities have been deducted.

Net Identifiable Assets, in the context of M&A, refer to the fair value of an acquisition target’s assets once the corresponding liabilities have been deducted.
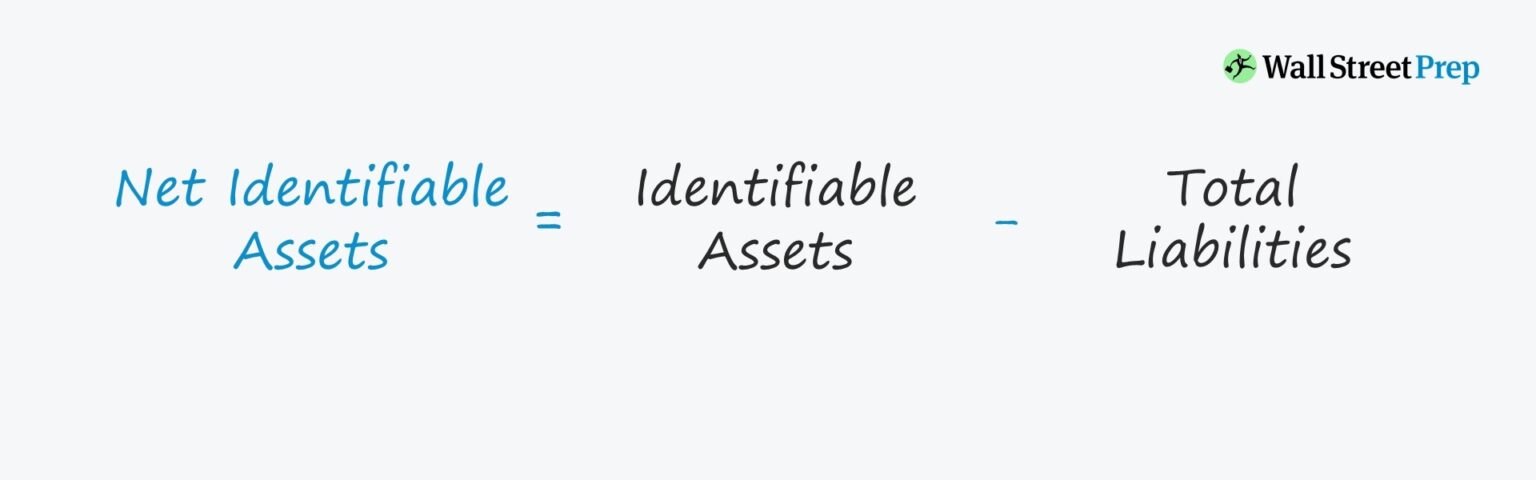
Net identifiable assets (NIA) are defined as the total value of a company’s assets net of the value of its liabilities.
Identifiable assets and liabilities are those that can be identified with a certain value at a specific point in time (and with quantifiable future benefits/losses).
More specifically, the NIA metric represents the book value of assets belonging to an acquired company once liabilities have been subtracted.
It is important to note that the terms:
The formula to calculate a company's net identifiable assets is as follows.
Formula
- Net Identifiable Assets = Identifiable Assets - Total Liabilities
The value of a target's assets and liabilities is assigned a fair value post-acquisition, with the net amount subtracted from the purchase price and the residual value recorded as goodwill on the balance sheet.
The premium paid over the value of the target's NIA is captured by the goodwill line item on the balance sheet (i.e. excess over purchase price).
The value of goodwill as recognized on the books of the acquirer remains constant unless the goodwill is deemed to be impaired (i.e. the buyer overpaid for assets).
Goodwill is NOT an “identifiable” asset and is only recorded on the balance sheet post-acquisition for the accounting equation to remain true — i.e. assets = liabilities + equity.
Suppose a company has recently acquired 100% of a target company for $200 million (i.e. asset acquisition).
In an asset acquisition, the target’s net assets are adjusted for both book and tax purposes, whereas in a stock acquisition, the net assets are written up for just book purposes.
The fair market value (FMV) of the target’s net identifiable assets on the date of the acquisition is $180 million.
Considering the FMV of the target's NIA is greater than its book value (i.e. $200 million vs $180 million), the acquirer has paid $20 million in goodwill.
The $20 million is recorded on the balance sheet of the acquirer because the acquisition price exceeds the value of the net identifiable assets.

Enroll in The Premium Package: Learn Financial Statement Modeling, DCF, M&A, LBO and Comps. The same training program used at top investment banks.


No comments yet.