How are Private Equity Salaries Different by Location?
In conclusion, one influential factor that impacts salaries in private equity is the location of the firm.
At the risk of stating the obvious, U.S. private equity firms with offices located in the "financial hubs" tend to pay a sizeable premium to their employees.
The most notable financial hubs in the U.S. are as follows.
- New York City (NYC)
- San Francisco
- Chicago
- Los Angeles (LA)
- Boston
Other cities with either a strong presence or an optimistic outlook in the coming years are the following:
- Miami
- Charlotte
- Atlanta
- Austin
- Dallas
Does Private Equity or Investment Banking Pay More?
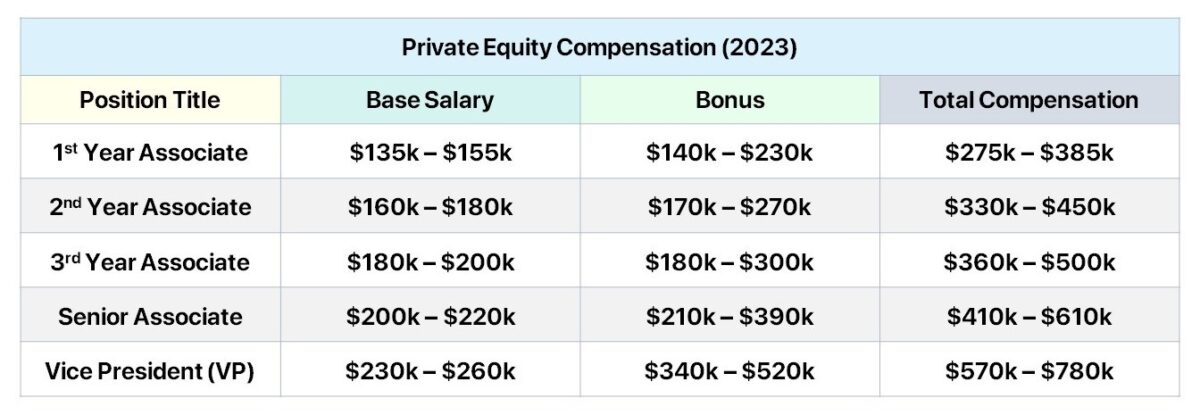
Since most private equity associates come with one to two years of investment banking experience, most private equity firms must pay above the average salary in investment banking to offer an incentive.
Besides the marginally reduced hours and being able to work on the buy-side – i.e. an investment role rather than advisory – the higher compensation is one reason many decide to exit to the buy-side and join a private equity firm.
However, there is one notable exception: Centerview Partners, an elite boutique highly regarded for paying its analysts salaries competitive with buy-side opportunities – hence, its industry-leading retention rate.
Given the recent widespread increases in pay for investment banking analysts in 2022, private equity compensation was expected to soon follow suit, which turned out to be right.
However, the mounting dry powder, rising interest rate environment, and the increase in bankruptcies in 2023 are factors contributing to widespread concerns about fewer hirings in the industry.
Therefore, it would be reasonable to expect a slowdown in hiring in the near term, particularly due to the sheer amount of hiring firms have done over the past couple of years, along with the macro issues and the increased cost of debt.
How Does Carried Interest Work in Private Equity?
Carried interest, often referred to as “carry”, is the share of profits that flows to the general partners (GPs) of a private equity firm.
The carried interest component functions as performance-contingent compensation, as it is deliberately intended to incentivize the firm to perform well and generate strong returns.
Unlike management fees, carried interest is typically only paid if the fund’s returns meet a certain minimum threshold.
The standard fee structure in the private equity industry is the "2 and 20" arrangement, which includes a 2% management fee and a 20% performance fee.
The actual payout can become complicated, however, due to factors like the catch-up clause and clawback provision.
The carried interest arrangement is specific to the private equity firm, but in general, members of the investment team should not expect to receive any proceeds until at the very least reaching the senior associate level, which is still uncommon.
Starting at the vice president (VP) level, one can expect to receive some carry, with the amount increasing for senior-level members like managing directors (MDs), as expected.
- Associate → No Carry
- Senior Associate → Uncommon
- Vice Presidents (VP) → Moderate
- Managing Directors (MD) + Partners → Significant
For mega-funds and larger-sized private equity firms with $1+ billion in assets under management (AUM), receiving carry at the lower levels (e.g. associates) is practically unheard of.
Private Equity Compensation: Industry Trends and Outlook
In the next section, we'll start by discussing the rising trend of private equity firms recruiting candidates straight out of an undergraduate program.
So, one key factor to consider in the private equity industry's compensation is the responsibilities of the associate, as not all "associate" positions are the same.
- Sourcing and Origination Team → If the role of the private equity associate is mostly related to sourcing and origination – i.e. reaching out to potential prospects via email and cold calling – the salary tends to be lower and relatively close to the salaries earned in investment banking.
- Investment Team → Conversely, if the associate's responsibilities mostly pertain to performing investment diligence, the salary can be expected to be on the higher end (and exceed most investment banks).
Obtaining an MBA is often a requirement for most private equity analysts to get promoted. Thus, joining a PE firm post-graduation comes with drawbacks and is not truly a "shortcut" into the buy-side.
On a similar note, non-traditional candidates from a unique background – such as consulting in a highly technical, niche field – can expect higher compensation.
Usually, such candidates will require an MBA to break into the private equity industry, but their technical expertise and network in a specific niche – rather than modeling skills and deal experience – is what causes their candidacy to stand out to a firm.
For instance, a former consultant who specializes in environmental sciences and truly understands the technical side of the products (and systems) could be a valuable addition to the investment team of an industrial technology private equity firm.
Still, the traditional one or two-year stint in investment banking and the subsequent exit into the private equity industry remains the most common pathway.


No comments yet.